The rent qualifies this loan. Your paycheck stays out of it.
The people we build this for.
Brokers, buy-and-hold investors, short-term-rental hosts and non-US buyers. The firms below are the ones you'll meet in our case studies.


“I ran the duplex at 7.25 and it cleared 1.21x, so I stopped reading. Track 2 put the same file at 0.96x once the new insurance quote went in. We restructured before the appraisal, not after.”


Price the deal in minutes
Enter the address, rent, and rate. Get two DSCR reads — one the lender uses, one that models real-world cash flow — plus break-even rate and cash-on-cash return, in under 60 seconds.

Compare the assumptions that shape a scenario
Run your file against Greenstreet's DSCR programs — filtered by credit score, LTV, and property type. Program availability, eligibility, pricing, underwriting, and funding are set by the lender on the file, not here.
Five questions to organize a scenario
Answer five questions about the property and borrower context. Pricing and program conclusions remain unavailable until approved source data is connected.
State rules, encoded and cited
Prepayment-penalty rules encoded for 47 states and DC, each with its statutory reference — reviewed annually, last confirmed January 2026. Includes MN, OH, PA, and NJ, where entity structure changes what you can close.
- Prepay allowed27
- Conditional18
- Practically prohibited3
- Not yet encoded3
Prepare a clearer scenario for review
One workflow prices it, structures it, and stress-tests it — no re-keying between steps and no surprises in the numbers. Figures shown are preliminary estimates, not a quote or a rate lock.
How much can you borrow on an investment property?
No credit pull. No income docs. We qualify the property, not you.
Rates are an indicative band as of June 2026, re-priced as the market moves. Taxes & insurance are estimated and reassessed at the purchase price. For business-purpose, non-owner-occupied investment property. DSCR floor ~1.00x; LTV cap varies by file. Not a loan commitment, approval, or offer of credit.
Prepayment-penalty rules, mapped state by state
Where a prepay penalty holds, where a dollar threshold flips it, and where it's effectively banned — encoded for 47 states and DC, with anything not yet researched flagged rather than guessed. Hover any state.
Which rental model fits the deal?
Property type changes the income story, operating workload, and financing path. Compare the upside and the friction before you underwrite the headline rent.
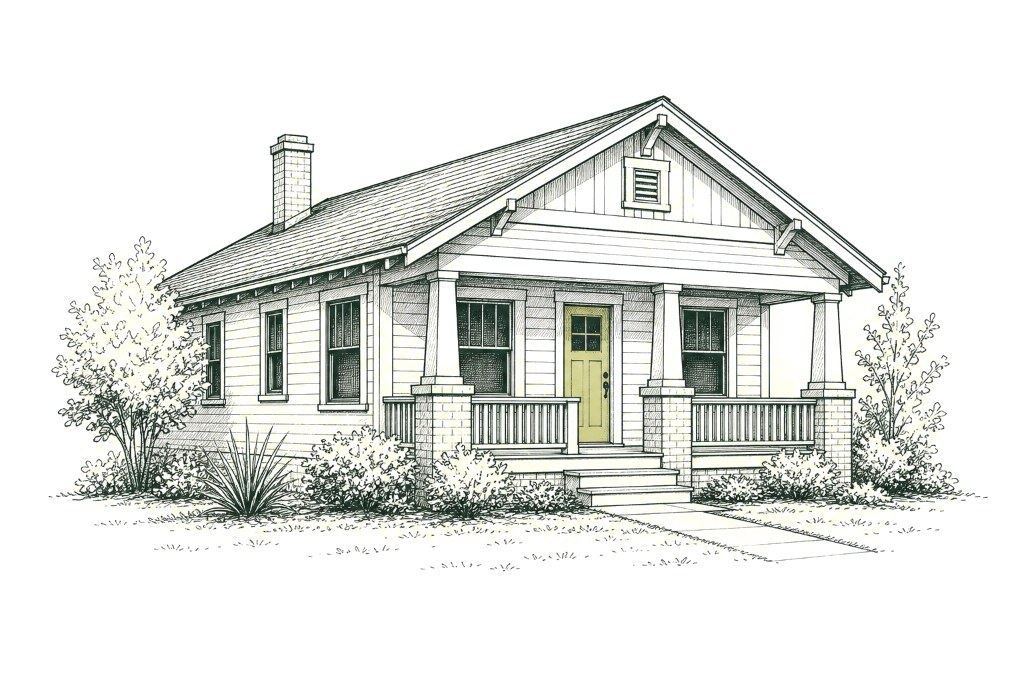
Single Family Rental (SFR)
Single Family Residential is the bedrock of DSCR lending. Qualification is 100% property-based using appraised market rent (FNMA Form 1007) or active lease agreement.
- Max leverage
- 80% LTV
- Coverage floor
- 0.75x Min DSCR
2–4 Unit Residential Multi-Family
Duplexes, triplexes and fourplexes put two to four rent streams against one mortgage payment, which is what tends to lift coverage per dollar of purchase price. Every unit's rent counts toward the same DSCR — vacant ones at the appraiser's market rent.
- Max leverage
- 75% LTV
- Coverage floor
- 1.00x Min DSCR
5+ Unit Commercial Multi-Family
Commercial multi-family DSCR loans bridge residential non-QM with institutional commercial underwriting. Valuations are driven by NOI and capitalization rates rather than residential comps.
- Max leverage
- 75% LTV
- Coverage floor
- 1.15x Min DSCR
Condominiums & Urban High-Rises
Condos often fail conventional Fannie/Freddie guidelines due to single-entity owner concentration, deferred maintenance, or active HOA litigation. DSCR non-QM fills this exact gap.
- Max leverage
- 75% LTV
- Coverage floor
- 1.00x Min DSCR
Short-Term Rentals & Resort Cabins
A nightly rental can gross more than the same house on a twelve-month lease — how much more depends entirely on the market, the season, and how the property is run. What matters for the loan is that short-term-rental programs can qualify the file on projected or documented nightly revenue instead of the lower long-term rent figure.
- Max leverage
- 75% LTV
- Coverage floor
- 1.00x Min DSCR
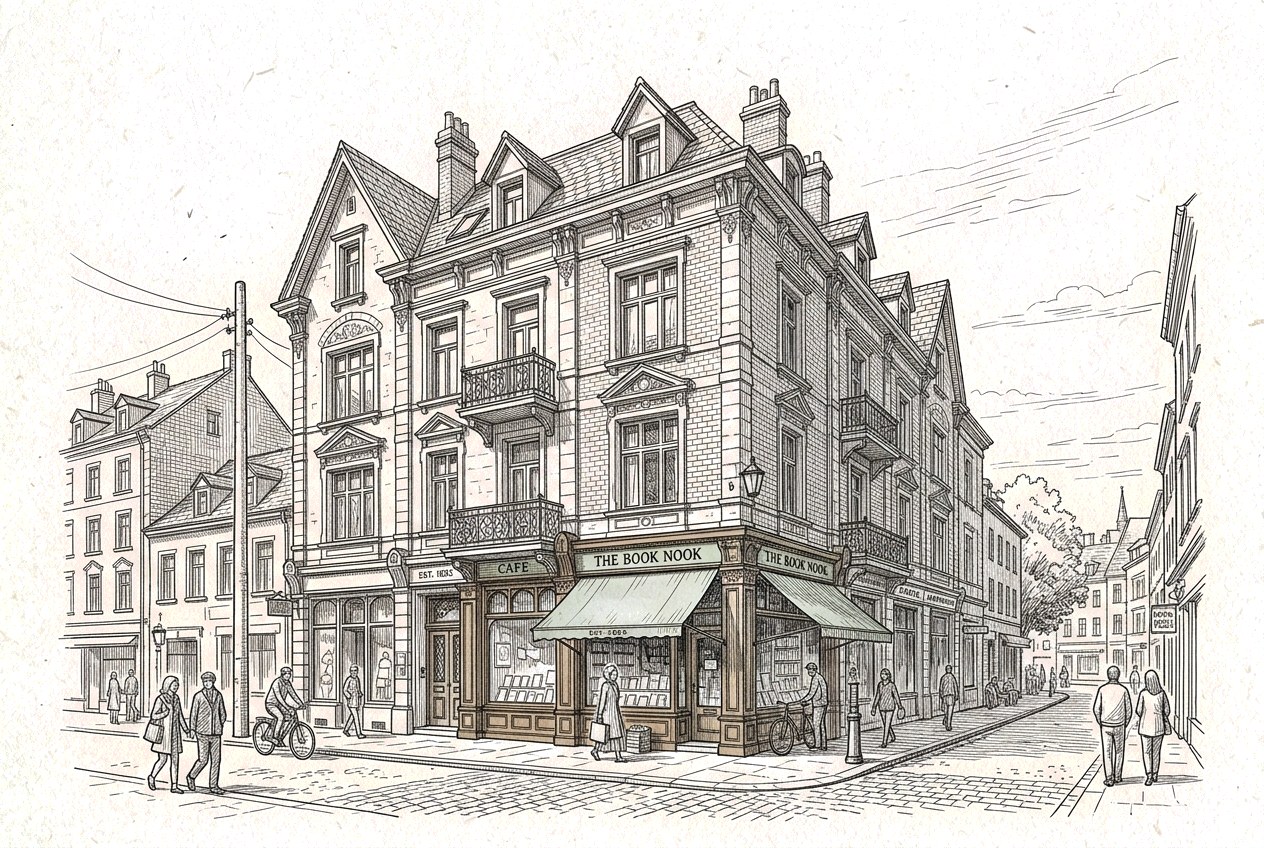
Commercial & Mixed-Use Storefronts
Mixed-use storefront properties offer dual revenue streams: stable long-term commercial retail tenants on NNN leases combined with residential apartment rents above.
- Max leverage
- 70% LTV
- Coverage floor
- 1.20x Min DSCR
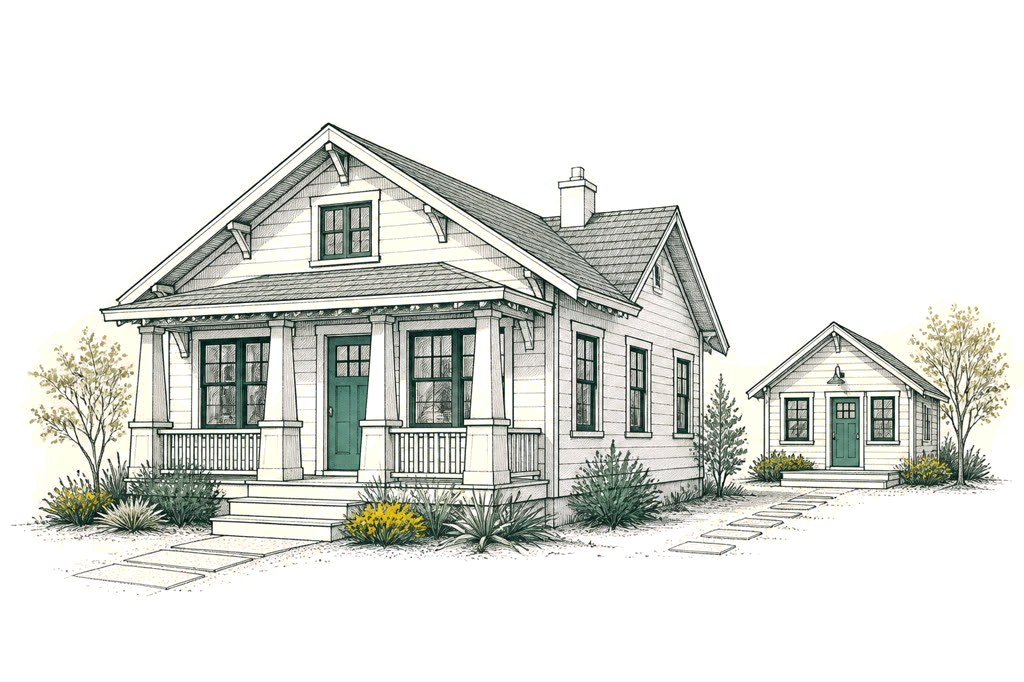
Primary Rental with an Accessory Dwelling Unit
A legal ADU can add a second rent stream and improve land efficiency, but permitting, utility configuration, appraisal treatment, and lender eligibility must all line up.
- Max leverage
- Program-specific
- Coverage floor
- Case-by-case
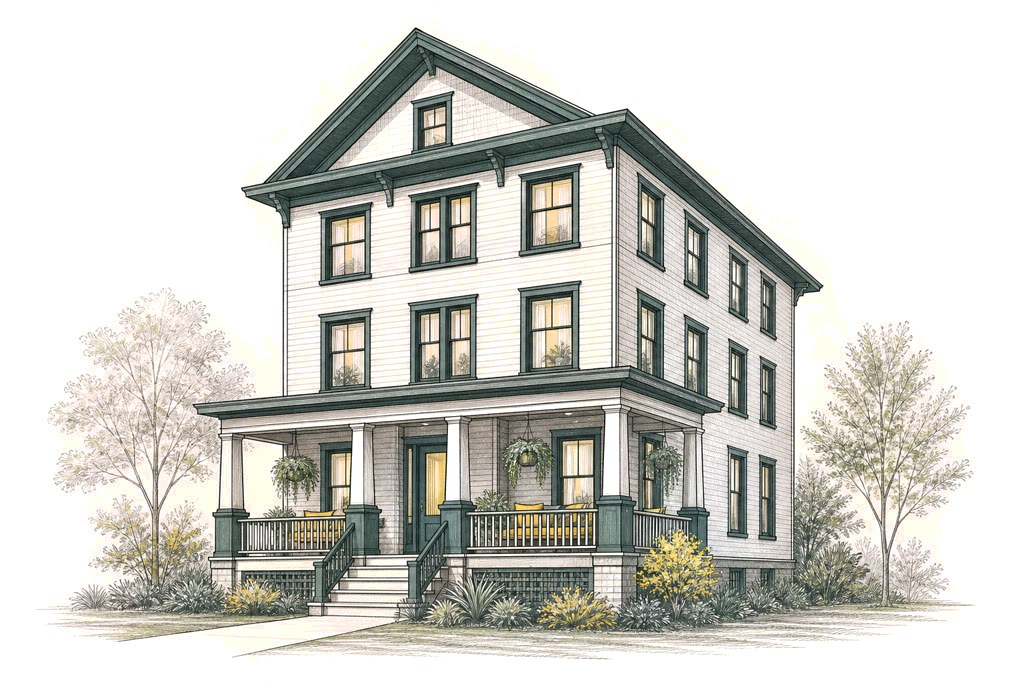
Student Housing & Co-Living Rentals
Leasing by the room can increase gross income, but the operating model behaves more like hospitality: frequent turns, shared-space wear, local occupancy rules, and active management matter.
- Max leverage
- Program-specific
- Coverage floor
- Lease-dependent
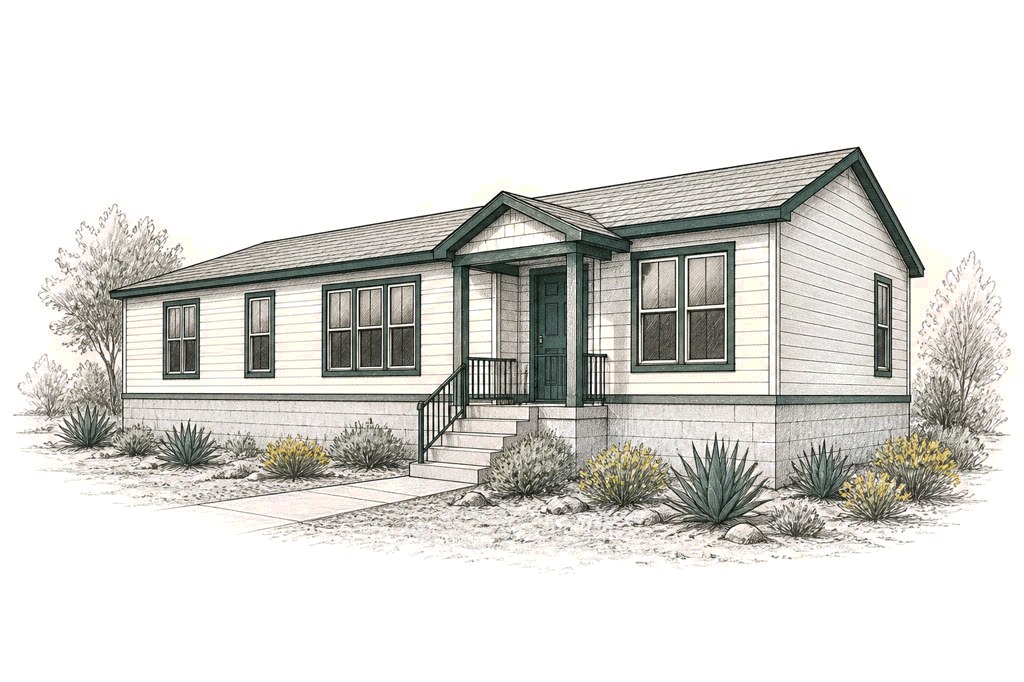
Manufactured & Modular Rental Homes
Manufactured and modular homes can offer a lower acquisition basis, but financing and resale depend on whether the home is real property, permanently affixed, insurable, and supported by comparable sales.
- Max leverage
- Program-specific
- Coverage floor
- Case-by-case
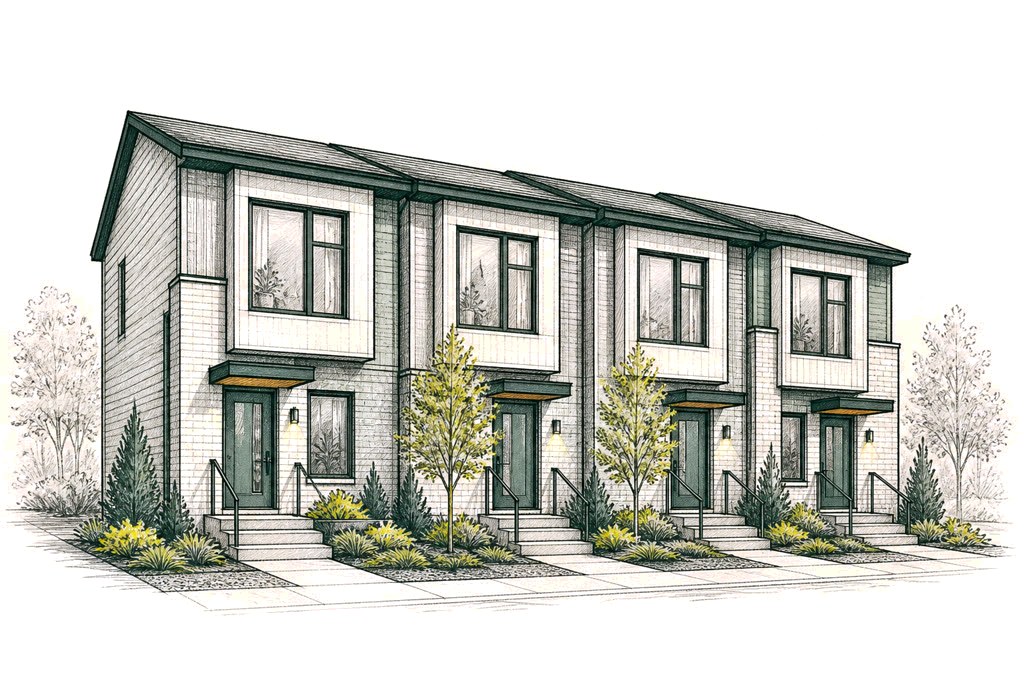
Build-to-Rent Townhome Communities
Build-to-rent combines residential tenant demand with community-scale operations. Standardized units can be efficient, but development and lease-up risks arrive before stabilized DSCR financing is available.
- Max leverage
- Stage-dependent
- Coverage floor
- Stabilized file
Watch the Greenstreet rebuild
Three deals, and the number that decided each one
Maeve Brennan
Acquisitions, Marlowe Asset Group — 22 doors, Ohio and Indiana
Ramón Aguilar
Buy-and-hold investor, Hadley Capital Partners — 9 doors across two states
Daniel Cho
Credit review, Sterling Bridge Partners
Names you'll meet in our case studies.