Each property qualifies on its own rent.
Edit the doorsRent, payment and DSCR for each property
Adjust any property's monthly rent and payment below. The 1.00x line is break-even — rent exactly equals the payment. A new door arrives with its own rent and its own ratio, and changes nothing about the ones already there.
What each deal is judged on.
Each deal is judged on its coverage, your credit score, the cash you hold after closing, and whether you buy in your own name or through an LLC.
The rent against the payment
Qualifying rent divided by the full monthly payment (PITIA). 1.00x is break-even; 1.25x is strong coverage, where best-tier pricing starts.
How DSCR is calculatedYou, not your paycheck
Your paycheck stays out of it. The credit, reserve and vesting rules are set program by program.
Credit, reserves and vestingThe property
Every rental model has a different income story, operating burden, and leverage ceiling.
Compare 10 property types
Choose the property. Then choose the debt.
Single Family Rental (SFR)
1-Unit Detached Homes, Townhomes & PUDs
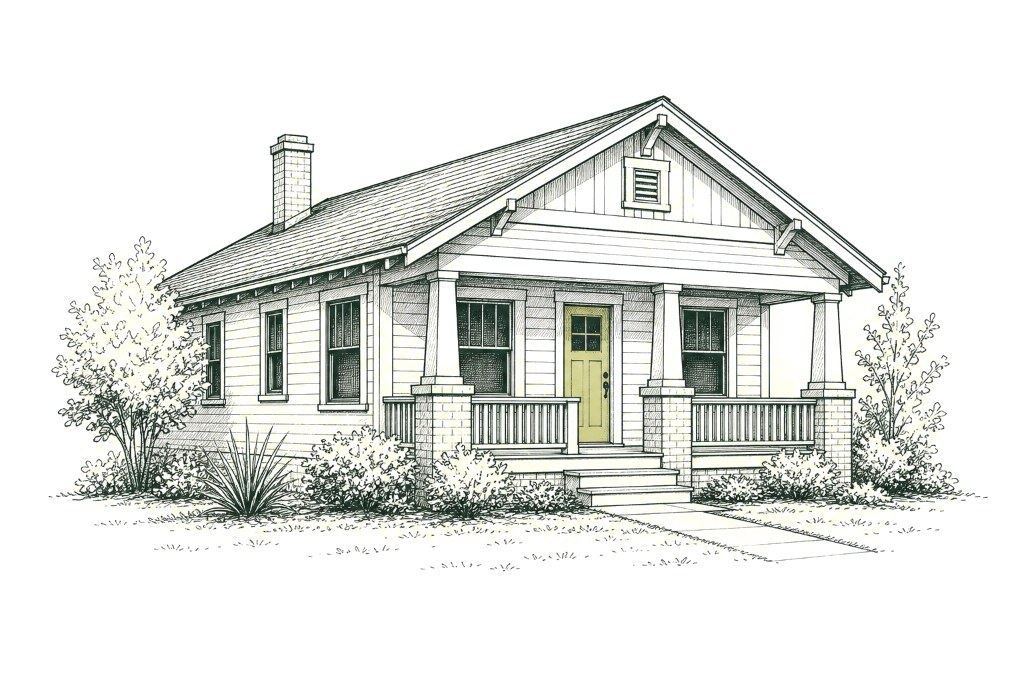
Why this lane fits
Single Family Residential is the bedrock of DSCR lending. Qualification is 100% property-based using appraised market rent (FNMA Form 1007) or active lease agreement.
A 30-Year Fixed DSCR loan locks low debt service for three decades with no refinancing risk. Switch to a 5/6 ARM if initial rate buydown is needed to clear 1.25x DSCR.
Buy-and-Hold Investors seeking long-term debt lock with zero W-2/Tax Return friction.
Tax edge, trade-offs and the decision checkpoint
What it gives you, what it costs, what to check first
Reclassify 20–25% of building basis into 5/7/15-year bonus depreciation under the 2025 tax law rules, creating massive year-1 passive loss offsets. Using them against wages and other ordinary income generally takes real estate professional status plus material participation in the rental, or material participation in a short-term rental; otherwise the passive-loss limits apply.
Advantages. Deep tenant demand and familiar lease structures in most markets Straightforward comparable sales can support valuation and resale Simpler operations than multi-tenant or mixed-use properties
Trade-offs. One vacancy can remove the property's entire rental income A major repair is supported by only one rent stream Scaling a scattered portfolio can increase travel and vendor complexity
Before you commit. Stress one full vacancy, a major system replacement, and realistic property-management costs before relying on the headline cash flow.
Terms assessed on every file
The five rows a lender reads for this property type
- Best loan structure: 30-Year Fixed or 5/6 ARM
- Qualifying income: LOWER of Signed Lease or Form 1007 Appraisal Market Rent
- No personal tax returns, W-2s, or DTI calculation required
- Qualify at 0.75x–1.00x DSCR with LTV adjustments (up to 80% LTV at 1.25x+)
- Borrower can vest in an LLC, S-Corp, C-Corp, or Individual name
- Prepayment-penalty rules encoded for 47 states and DC, each with its statutory citation — including the common 5/4/3/2/1 and 3/2/1 step-downs, where the fee shrinks every year you hold the loan
Underwriting referenceCoverage tiers, qualifying rent, reserves, tax and closing documents
Everything a DSCR Investor Needs to Know
No W-2s, no personal tax returns, and zero DTI calculations. Underwrite deals strictly on property rental coverage, credit score, reserves, and LLC vesting.
How Coverage Ratio Dictates Your Rate & Max LTV
Greenstreet models every deal on Dual-Track DSCR Science. Track 1 measures Lender Approval Qualification (Gross Rent ÷ PITIA). Track 2 measures Real Investor Net Cash Flow (factoring 7% vacancy, 8% property management, 8% maintenance and 5% capital-expenditure reserves, and property tax reassessments).
Two ways to measure coverage
Track 1 qualifies the loan; Track 2 is your real cash flow
| Coverage Floor | Purchase LTV | Refi LTV | Min FICO | PITIA Reserves | Pricing Impact |
|---|---|---|---|---|---|
| 1.25x+ (Strong Coverage) | Up to 80% | Up to 75% | 660+ | 3 Months | Standard Par Rate |
| 1.00x – 1.24x (Standard Floor) | Up to 75% | Up to 70% | 640+ | 6 Months | +0.25% Rate Adjustment |
| 0.75x – 0.99x (Low-Ratio) | Up to 70% | Up to 65% | 640+ | 6–12 Months | +1.5% Rate Adjustment |
| No-Ratio (< 0.75x or Vacant) | Up to 65% | Up to 60% | 640+ | 12 Months | +1.5% Rate Adjustment |
Notes on this table
Illustrative tiers, and what Min FICO means
Illustrative pricing tiers, not a live rate sheet — actual pricing runs through Greenstreet's engine and each program's own matrix. Scope: tiers from 640; programs start at 620.
Min FICO is the lowest published eligibility floor for that DSCR tier; credit score also changes the rate — see the rate bands.
Greenstreet Investor Scenario Suite
DSCR Coverage & Rates
The rent-to-payment ratio, the full monthly payment (PITIA) and where your file lands on the rate tiers.
Check my DSCRShort-Term Rental Tool
Underwrite Airbnbs and resort cabins using AirDNA projections or 12-month actuals.
Underwrite STRState Penalty Rules — 47 + DC
State-by-state prepayment penalty caps, thresholds and LLC exemptions.
View state lawsCost Seg & Tax Engine
Year-1 bonus depreciation under the 2025 tax law and passive loss offsets.
Run the tax engine10-Yr Cash Flow & IRR
Multi-year cash-on-cash yield, equity build and the IRR waterfall.
Model returnsCommercial 5+ & Mixed-Use
Commercial multi-family and mixed-use storefront properties.
Commercial DSCRReady to apply?
Tell us about the loan you want. We don’t pull your credit when you submit, and nothing here is an approval or a commitment to lend.
Questions on a deal? Review my deal — one workflow prices, structures, and stress-tests it, and your numbers are saved with the request.
Review my dealRun your next property's rent through Greenstreet — 60 seconds, zero credit impact.
Check my DSCR