The getaway that pays for itself.
Keep up to 14 nights a year, rent the rest, and let your escape carry part of its own payment.
Slide the month. Watch it pay you back.
Set the nights you rent each month and the nights you keep each year. Past 14 of your own, the loan type changes.
Six shapes a second home takes.
The structure changes what you can let, and what a lender will count.
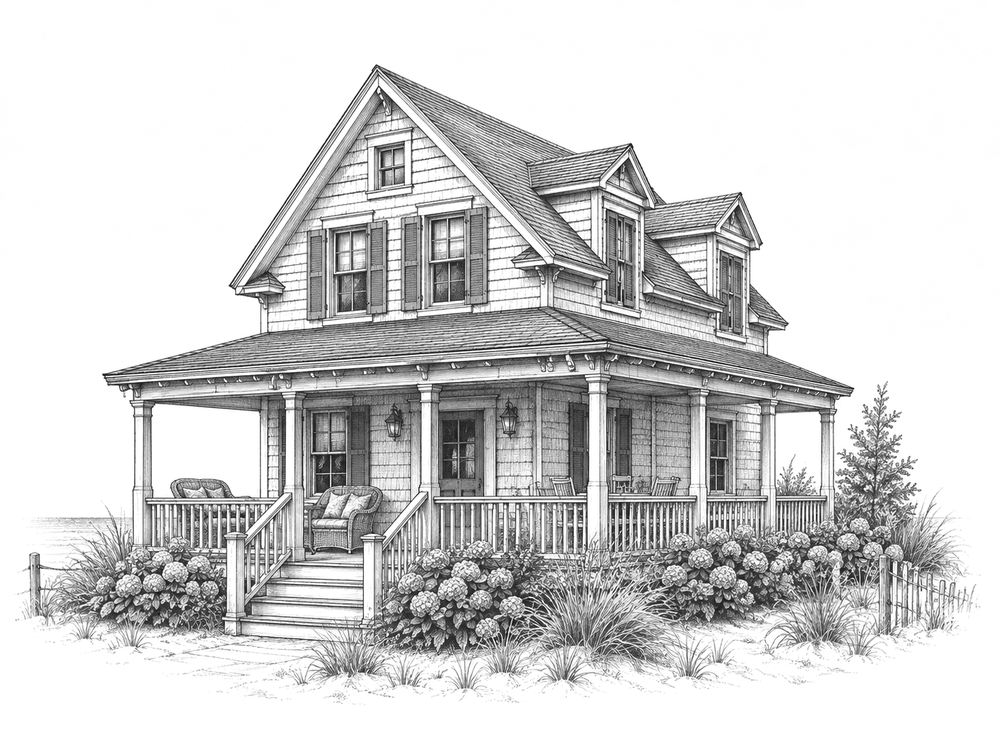
Coastal cottage
The classic let: your two weeks in season, nightly bookings around them, and a porch that books itself.
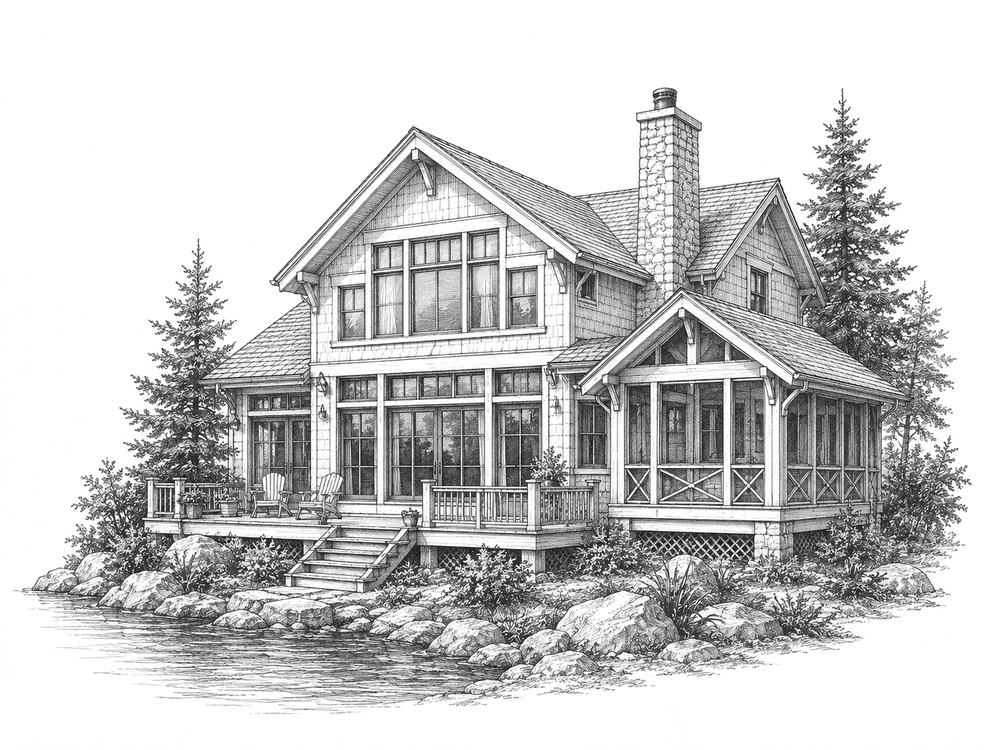
Lake house
Bigger footprint, longer stays. Weekly summer lets tend to carry more of the payment than nightly ones.
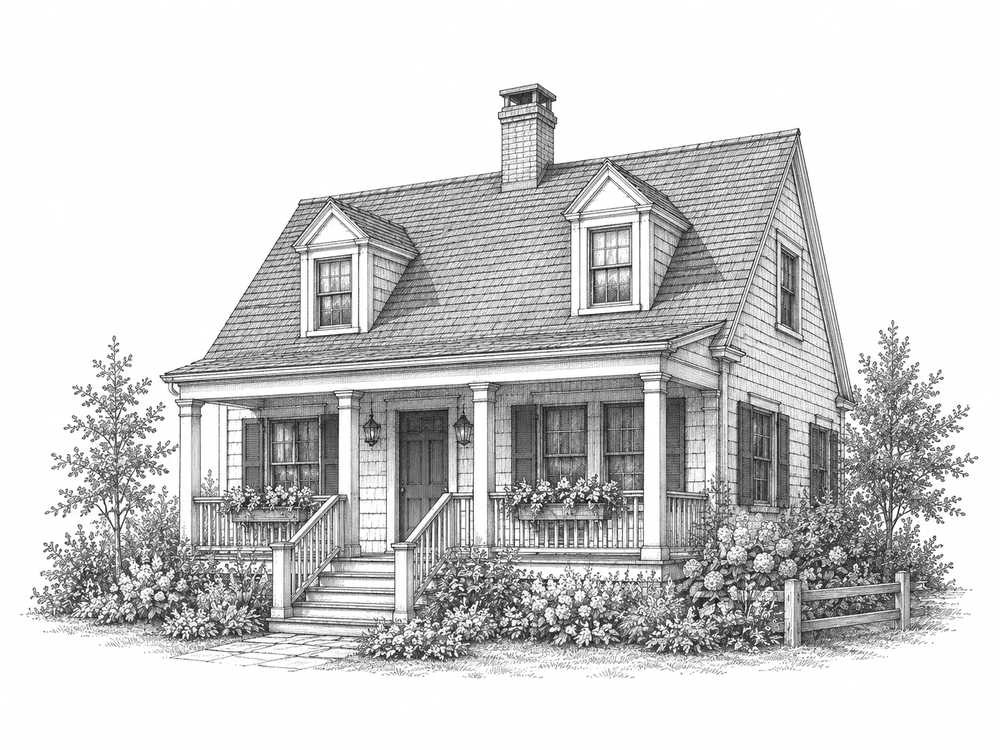
Cape Cod cottage
Shoulder-season demand is the swing factor — the calendar, not the headline nightly rate, decides coverage.
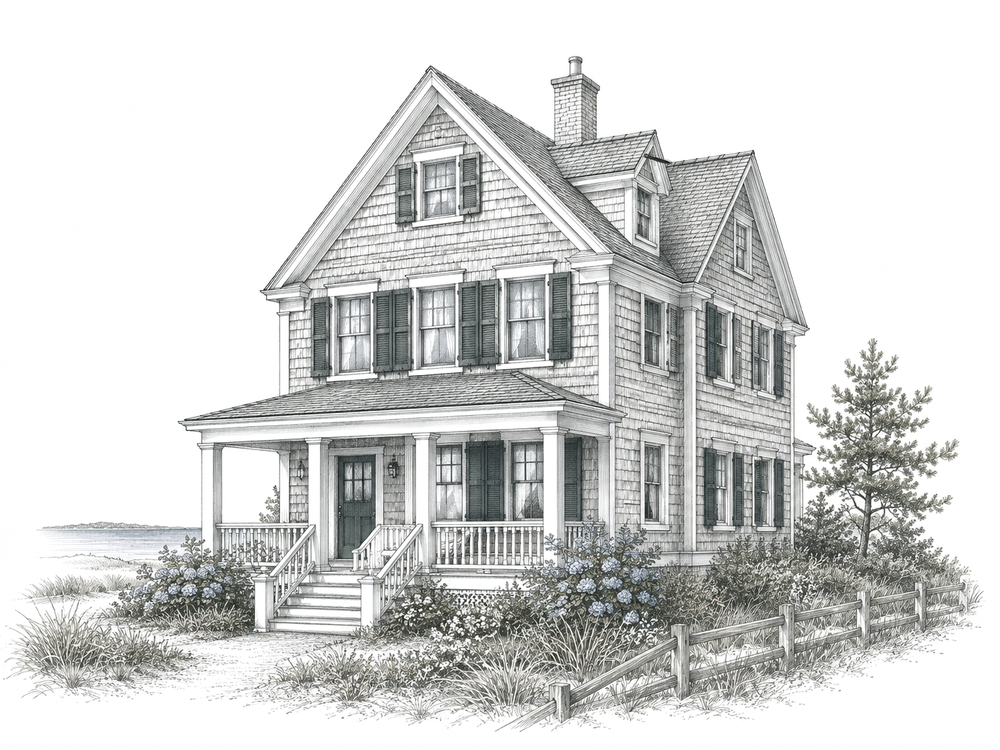
Shingle-style retreat
Higher basis, longer bookings, fewer turnovers. Coverage leans on rate per stay rather than nights filled.
Mediterranean-style villa
A warm-market staple. Pool and grounds upkeep is the line most first pro-formas leave out entirely.
Modern coastal retreat
Newer build, lower deferred maintenance, higher insurance. The trade shows up in reserves, not in rent.
A second home, financed like the asset it is.
Qualify on the rental nights
We model the income from the nights you let — not your salary. On the DSCR path, keep your own use to 14 nights a year.
Run my second homeNo second-home income docs
Held to 14 personal nights a year, it's a DSCR investment loan: the property's rent qualifies, so there's no DTI squeeze on top of your primary mortgage.
How rent-based qualifying worksSTR-aware underwriting
Seasonal nightly income is modeled honestly — the number holds when the off-season hits.
Slow months, underwritten
Ready to apply?
Tell us about the loan you want. We don’t pull your credit when you submit, and nothing here is an approval or a commitment to lend.
Questions on a deal? Review my deal — one workflow prices, structures, and stress-tests it, and your numbers are saved with the request.
Review my dealPrice your getaway as a DSCR loan (14 personal nights a year or fewer) — 60 seconds, no credit pull.
Run my second home