Airbnb DSCR loans that survive the slow months.
We model your rental month by month, so you see the slow months before a lender does.
The deal has to survive February — not just July.
Set your rate and occupancy. Months under the line don't cover the payment, so underwrite from the trough, not the peak.
February is not everyone’s slow month.
Underwrite from the trough, but which month that is depends on what you own.
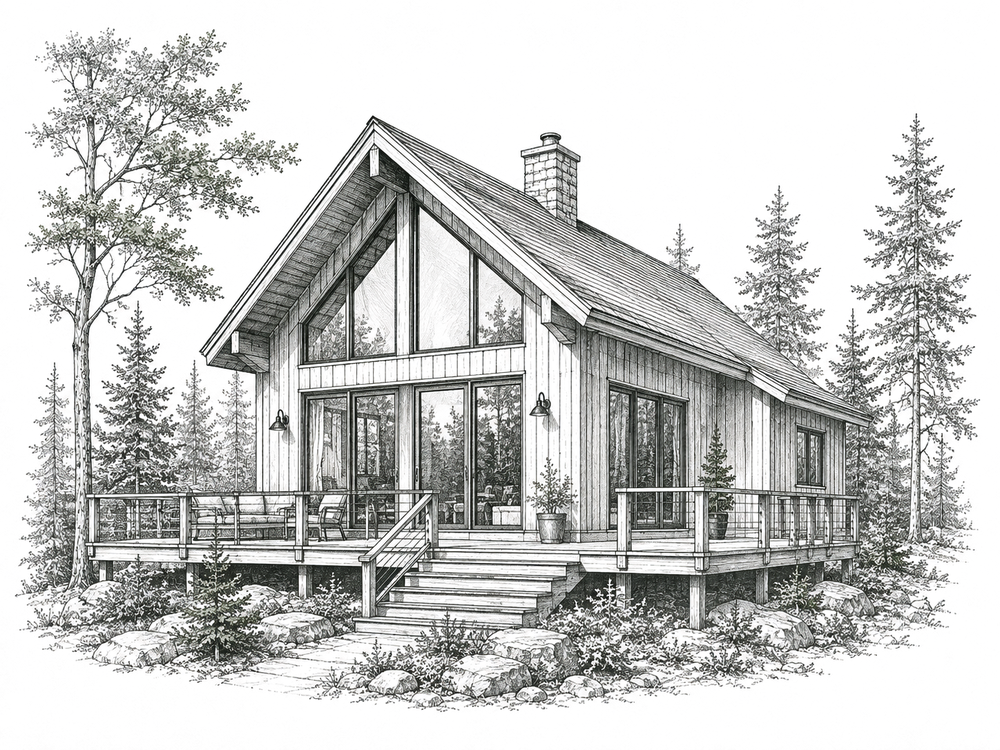
Summer-peak cabin
Warm-season demand, quiet winter. This is the shape the calculator above models, so its trough and yours line up.
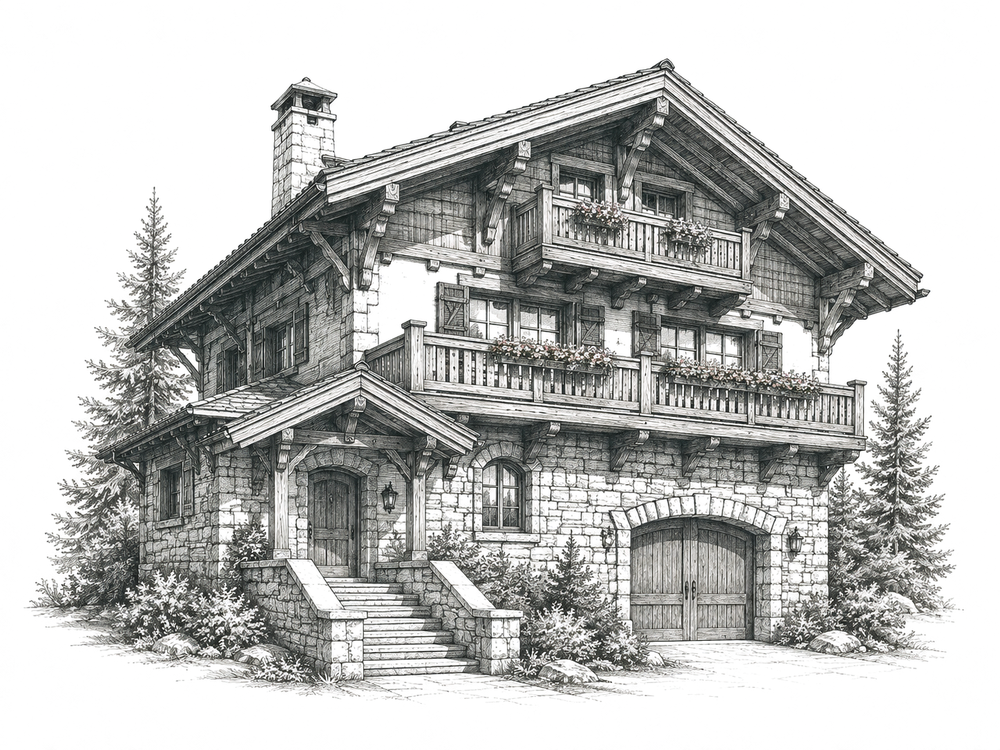
Ski chalet
The curve inverts. The deep months are the ones a summer model treats as peak, so underwrite the off-season it calls busy.
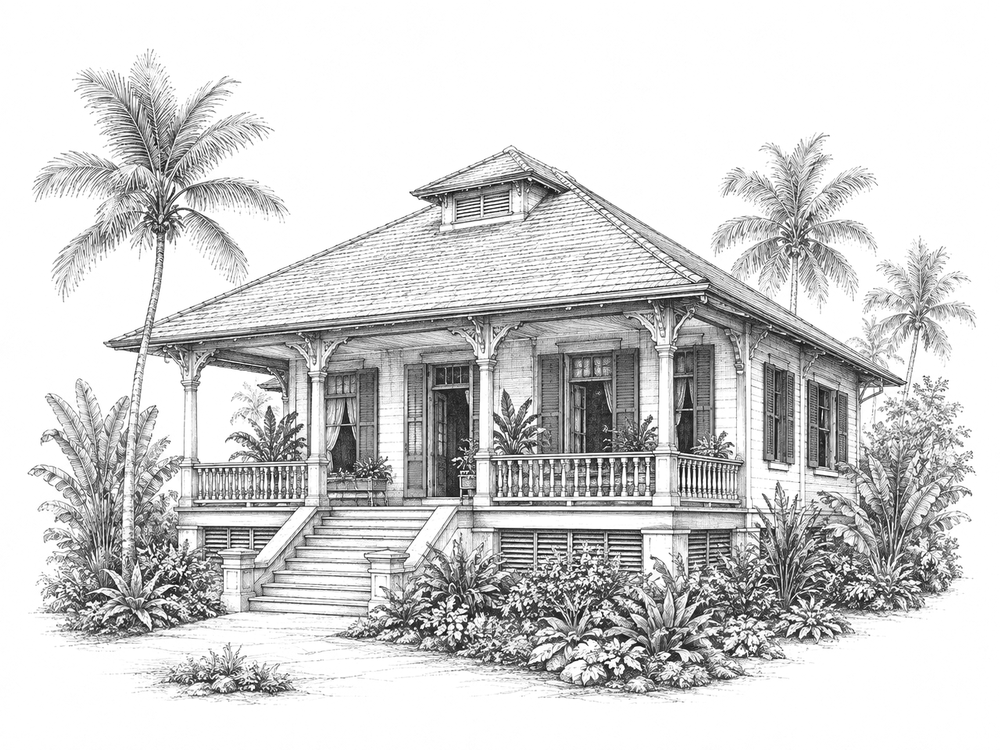
Warm-climate bungalow
Flatter demand across the year with a weather-driven dip. The trough is shallower, but it is still the month that has to clear.
STR income, underwritten honestly.
Real ADR × occupancy
Market data, not a host's best week. The number is the one a lender will actually fund.
Underwrite my STRSeasonally stress-tested
We check the trough month and a rate rise before you commit — no off-season surprise.
Stress-test a dealLong-term fallback
If the STR number is thin, the long-term lease can carry the file instead — the engine models both and shows you which is stronger.
Check my DSCR
How this is calculated
The revenue ribbon models income the way a short-term rental actually behaves. Average nightly rate × occupancy gives an average month, and a summer-peak seasonal shape spreads it across the year. Each month is then set against the monthly payment — surplus above the line, shortfall below — and the worst month is the one to underwrite from.
The seasonal shape is there for orientation, not as market data. Real underwriting uses the property's own platform history for the market it sits in, and the trough is not always February.
What qualifies
Lenders qualify short-term income more conservatively than the ribbon's gross. They use the lowest of three figures:
- the Form 1007 long-term market rent, which controls when the property has no STR history;
- an AirDNA-style projection, counted at 80%;
- documented platform payout history, counted at 90% — discounted less, because it is evidence rather than a forecast.
All 7 published Greenstreet programs are marked STR-eligible. Some set their own STR terms: Greenstreet Birch lists “STR to 80% LTV” and Greenstreet Aspen lists “STR (1.15 DSCR, 720)”.
STR legality is a city and county question, and Greenstreet holds no municipal STR dataset — confirm the local rule before you rely on the income.
STR UnderwritingFAQ: STR qualifying incomeGlossary: qualifying rentSTR income in a DSCR scenario
Ready to apply?
Tell us about the loan you want. We don’t pull your credit when you submit, and nothing here is an approval or a commitment to lend.
Questions on a deal? Review my deal — one workflow prices, structures, and stress-tests it, and your numbers are saved with the request.
Review my dealRun your nightly rate and occupancy through the STR engine — month by month.
Underwrite my STR